Marijuana rescheduling was supposed to hand U.S. cannabis companies a measure of financial relief after years of waiting. Instead, a fresh procedural dispute is threatening to stretch out a review process that has already dragged on far longer than the industry expected.
A Government Report Becomes a New Sticking Point
The latest snag centers on a Government Accountability Office report examining how federal agencies evaluate controlled substances. Opponents of rescheduling want that report entered into the administrative record, along with additional testimony and document access. The DEA says it has no objection to including the report itself. But the broader requests - more testimony, more discovery - are exactly the kind of procedural add-ons that can quietly add months, or longer, to a rulemaking that was already years in the making. For an industry that has learned to treat every federal deadline as provisional, this is familiar territory.
Here's the catch: rescheduling isn't a simple up-or-down vote. It moves through an administrative process that allows interested parties to contest evidence, request hearings, and introduce new material into the record. Each procedural request, even a modest one, can reset timelines. That's frustrating for operators who built financial models around a Schedule III shift arriving on a certain horizon. In practice, though, this is how federal rulemaking works, and cannabis companies are discovering that the normal pace of Washington bureaucracy doesn't bend just because an industry is impatient.
Why 280E Still Shapes the Balance Sheet
At the center of the frustration is Section 280E of the federal tax code. Because marijuana remains Schedule I for much of the industry, cannabis businesses generally can't deduct ordinary operating expenses - payroll, rent, advertising - when calculating federal taxable income. That's a burden most other retailers simply don't carry. Moving marijuana to Schedule III would lift that restriction for qualifying activity, potentially freeing up real cash for reinvestment, debt reduction, or shareholder returns.
Green Thumb Industries (OTC: GTBIF) is a clear example of a company positioned to benefit, though the exact savings would hinge on final rules and how regulators implement them. Until then, Green Thumb keeps operating under a tax structure that penalizes basic business expenses most companies take for granted.
The Numbers Behind the Noise
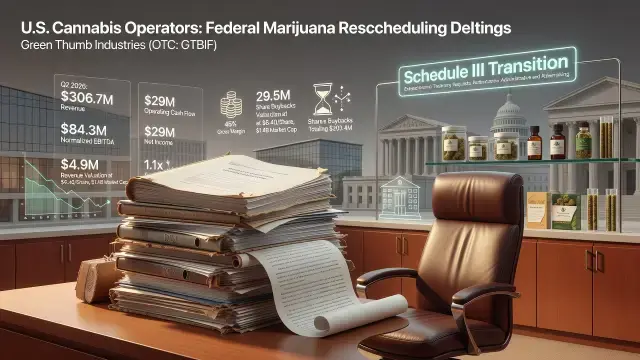
What's striking here is that Green Thumb is still generating real cash despite the 280E drag. The company posted $29 million in operating cash flow during Q2 2026, with revenue of $306.7 million and normalized EBITDA of $84.3 million. Net income came in at $4.9 million. None of that depends on a rescheduling decision; it's the output of an operating retail and wholesale network functioning under current law.
At roughly $6.40 per share, Green Thumb trades at about $1.4 billion in market capitalization - close to 1.1 times annualized second-quarter revenue. That's a modest multiple for a company with an established dispensary footprint, positive earnings, and consistent cash generation. There's room for the valuation to improve if margins stabilize, though gross margin slipped to 45% in Q2 from 49.9% a year earlier, a reminder that wholesale pricing pressure and competitive retail markets are squeezing operators across the board, not just the smaller ones.
- Section 280E blocks deductions for payroll, rent, and advertising under federal tax law
- Rescheduling to Schedule III would remove that restriction for qualifying cannabis activity
- Procedural disputes over administrative records can extend federal rulemaking timelines
- Gross margin compression reflects broader pricing pressure across state cannabis markets
Buybacks and the Case for Patience
Green Thumb has used its financial flexibility to repurchase shares, buying back about 29.5 million shares for $203.4 million by quarter's end. That reduces the outstanding share count and gives remaining shareholders a larger slice of the business - not a flashy move, but a disciplined one for a company operating under a tax code stacked against it.
Federal policy remains the biggest near-term catalyst for Green Thumb and for the sector broadly. But the investment case, and the operational case, shouldn't rest entirely on what happens inside a DEA docket. Pricing pressure, regulatory uncertainty, and uneven growth across state markets are real risks that won't disappear even if rescheduling advances. A delayed decision is a genuine frustration for shareholders and operators alike. It doesn't, however, erase the cash flow, the retail infrastructure, or the earnings already on the books.